

October 2026 Issue #12 | |||
Stocks and Bonds Are Acting Confused | |||
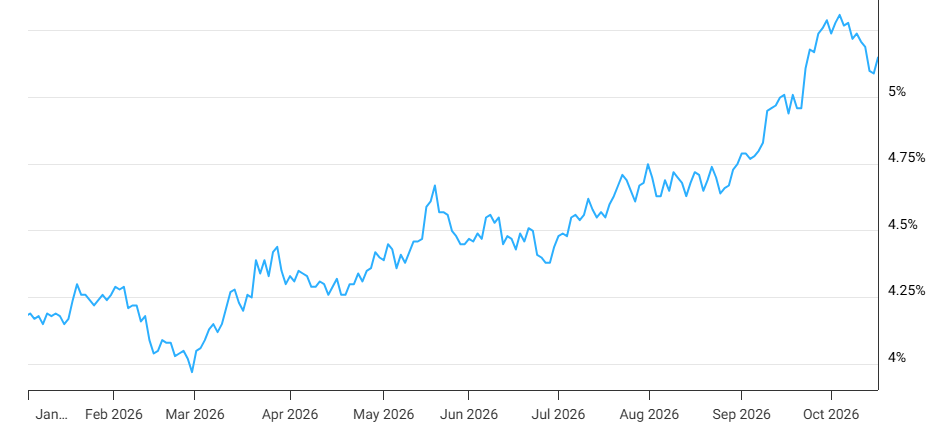
THE BIG 3__ The Great BifurcationIndices near records, most individual stocks, not so much. __ Bonds are not HappyThe market controls interest rates, not the Fed. __ Election VolatilityMidterms make for bad commercials and high market volatility. | 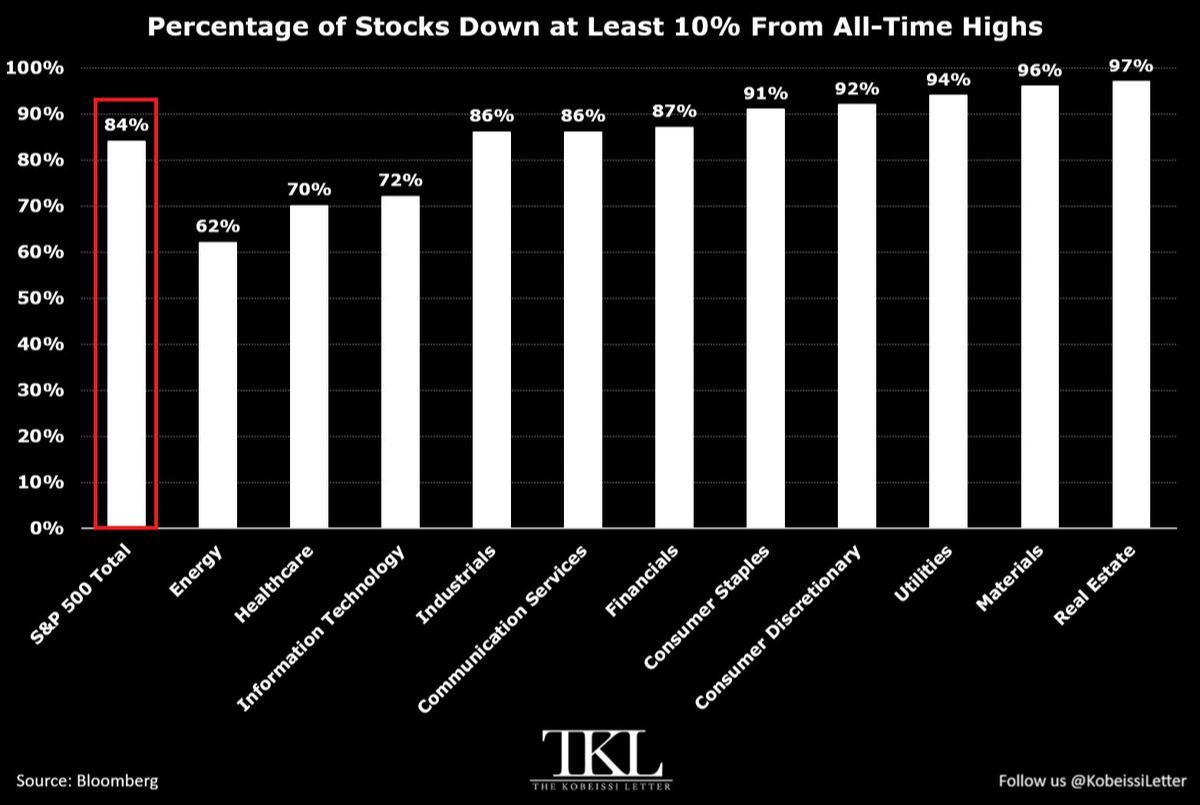 | ||
The Great BifurcationThe S&P 500 at a record ≠Stocks at record highsThe late Jack Bogle, founder of Vanguard, would have gotten a kick out of US stock market in 2026. If you remember, he was one of the loudest proponents of index funds. More specifically, he famously suggested the broad public should only buy the S&P 500 and hold it forever. 2026 has turned out to be one of those years (so far). Contrary to popular belief, volatility has remained relatively muted for the majority of the year, and only a handful of widely held stocks are driving index performance. This is made even more clear when we note the divergence in performance of the largest constituents in the S&P relative to the broader index. At the end of Q3, roughly 84% of stocks were more than 10% below their all-time highs. When you combine that with the fact that 2 companies are contributing +/- 30% of the total S&P earnings growth, we might very well be watching the most concentrated market in history. | |||
Election Vol.Midterm elections often result in a nothing burger after it is all said and done. What we are seeing:
| |||
 | The Bottom LineVery rarely do we find ourselves in a calm geopolitical environment with low inflation and accelerating growth. Those rare seasons make investing seem easy. 2026 has been anything but calm, yet thoughtfully diversified portfolios are at or near their all-time highs. We don’t pretend to be smarter than the market, and we will always respect the possibility of a market selloff. As such, we are focusing on adding additional exposure to non-correlated asset classes and preparing for the uncertainty that lies ahead. | ||
Any opinions are those of Alexander Leonida. The information contained in this document does not purport to be a complete description of the securities, markets, or developments referred to in this material. There is no assurance any of the trends mentioned will continue or forecasts will occur. The information has been obtained from sources considered to be reliable, but CFG does not guarantee that the foregoing material is accurate or complete. This newsletter: (a) is not an official transaction confirmation or account statement; (b) is not an offer, solicitation, or recommendation to transact in any security; and (c) may not be retransmitted to, or used by, any other party. Investment products are: Not deposits. Not FDIC or NCUA insured. Not guaranteed by the financial institution. Subject to risk. May lose value.